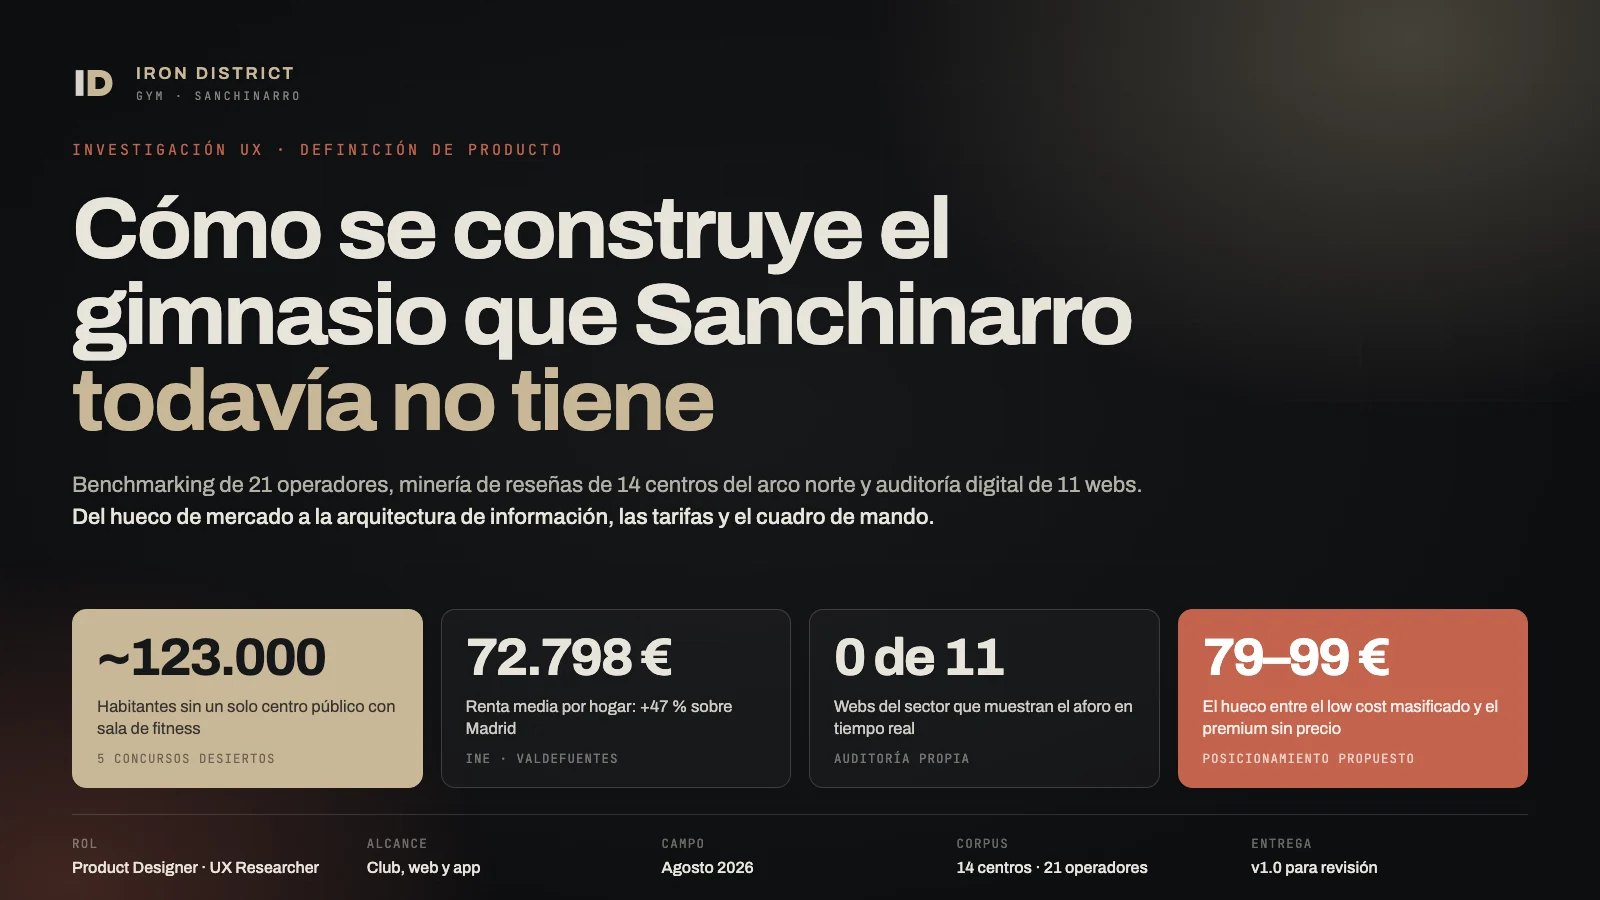
How you build the gymthat Sanchinarrostill doesn't have
UX research and product definition for the opening of Iron District Gym: competitive benchmarking of 21 operators, review mining across the competition, information architecture, and the design of the physical and digital product — from the floor area split to the price table.
Research · Benchmarking · Architecture · Product definition — 2026
The gap isn't in the equipment catalogue. It's in capacity, guidance and commercial honesty.
Sanchinarro and its northern arc hold some 123,000 residents with the highest household income in Madrid, without a single public sports centre with a weights room, and with a private offer that residents themselves describe, almost unanimously, with the same word: overcrowded.
~123,000
Residents across Sanchinarro, Valdebebas, Las Tablas and Montecarmelo
Direct market
€72,798
Average household income in Valdefuentes: 47 % above the Madrid average
INE · income atlas
0
Municipal sports centres with a fitness floor anywhere in the northern arc
5 failed tenders
50 %
Of those who don't lift say they feel out of place in the weights area
Les Mills · n>10,000
Methodological note read before quoting
The “interviews” in this report are not face-to-face interviews: they are a corpus of real public reviews treated with qualitative technique (review mining). The quoted verbatims are literal and attributed to their source; the archetypes are constructs derived from patterns, not real people.
The card sorting is designed and run on that corpus: its groupings are grounded hypotheses, pending validation with 15-20 real participants before the navigation is frozen. A good share of the reviews is between one and four years old. Everything I could not verify is flagged as such throughout the document.
The six conclusions
Conclusions ordered by their consequence on the product
#
Conclusion
Evidence
01
The dominant pain in the area is time-of-day, not product. Overcrowding between 17:00 and 21:30 shows up in every high-volume club analysed. Iron District competes on managed capacity, not on machine count.
7 of the 14 clubs in the corpus
02
Your customer is not the powerlifter. It is the 50 % who feel out of place in the free-weight area and the 37 % who don't know how to progress. Above all women aged 35 to 55 and adults over 50.
Les Mills 2026 · n>10,000
03
Transparency is the cheapest differentiator there is. The direct competitor demonstrably loses customers by refusing to give prices by phone or web: there are reviews from people who ruled themselves out without ever setting foot inside.
5+ reviews · Infinit Sanchinarro
04
Nobody in the Spanish sector shows live capacity on their website. Nor a real facility tour. Two clean, cheap gaps that answer exactly the anxiety holding back one in three people.
Audit of 11 websites
05
Satisfaction in the area is anchored in people, not brands. “Claudia”, “David”, “Mónica and Raúl” are named in dozens of reviews. The only club that systematically replies to reviews is also the best rated.
Tubau GYM · 4.9/5 across 196 reviews
06
The whole economics of the business rests on one metric: visit frequency. Two weekly visits equal seven months of average tenure; three or more, twenty-eight.
IHRSA · Paul Bedford research
Recommended positioning
“The strength club where there is always a free rack and you always know what today's session is.” A strength boutique with coaching included, capacity managed by zone and zero commercial friction.
Fee range €79-139/month, no lock-in, no joining fee and cancellation in one click: above the area's low cost (€25-36), below the Madrid boutique average (€122) and below premium (>€130).
(01) — Context and method
A brief with a name and an identity, but with no product defined
Define the product —physical and digital— of a gym about to open in Sanchinarro, with a name and an identity already started in Figma, and get to an actionable information architecture for the website.
With no members yet to ask, the research leans on a corpus of public reviews of the competition: it is the closest you can get to the voice of the user before opening the doors.
Desk research
Market and territory context
Demographics and income for Valdefuentes and neighbouring districts (INE, Madrid City Council, idealista/maps), the state of municipal sports facilities, and sector reports: España Activa/Deloitte 2026, EuropeActive, 2Playbook Intelligence, ACSM and the Les Mills Global Fitness Report 2026.
Qualitative research
Review mining of the competition
Thematic analysis of public reviews across 14 clubs in the northern arc: Google Maps via aggregators, neighbourhood forums for Sanchinarro, Las Tablas, Valdebebas and Montecarmelo, and published complaints from OCU and FACUA. Open coding of complaints and praise, grouped by frequency and by club.
Benchmarking
21 operators, direct and indirect
Low cost and mid-market clubs in the area, strength and CrossFit boutiques in Madrid, premium chains (Metropolitan, We/On, GO fit), recovery studios and international references (Third Space, Equinox, Life Time).
Heuristic analysis
11 gym websites and 8 apps
Literal extraction of every main menu, plus an audit of nine capabilities: price without sign-up, joining online, public timetables, booking, tour, live capacity, blog, shop and cancellation. App Store and Google Play reviews reviewed to identify the recurring product failures.
Why review mining and not a survey
A survey of local residents would have measured stated intent about a club that doesn't exist yet. Reviews measure consummated behaviour: people who already paid, who already left, and who explain why. The bias is known —extremes get reviewed more— and it is offset by cross-checking the corpus against sector data and by declaring it on every claim.
(02) — The territory
A market of 123,000 people with no public offer, and none coming
Sanchinarro is not an administrative district: it is part of Valdefuentes (Hortaleza), together with Valdebebas, Las Cárcavas and El Encinar de los Reyes. All official statistics “for Sanchinarro” are in fact for Valdefuentes.
72,554
Residents in Valdefuentes
+13 % in 4 years
35.4
Average age, against roughly 45 for the city of Madrid
The young district of the city
53.4 %
Population between 30 and 64
Core of the fitness market
8.2 %
Over 65, against roughly 21 % for the city of Madrid
An exceptionally young profile
The northern arc, district by district
Population, 10-year growth and sale price per district
Area
Population
10-year growth
Sale €/m²
Predominant age
Sanchinarro
34,495
+16 %
5,917
<19 years
Las Tablas
33,316
+25 %
5,311
<19 years
Valdebebas
25,004
+251 %
6,080
36-49 years
Montecarmelo
23,506
+29 %
6,553
<19 years
Virgen del Cortijo-Manoteras
6,956
+15 %
5,869
>65 years
On top of that comes Solana de Valdebebas, with 1,393 approved homes and ground broken in January 2025 (≈ +3,500 residents), plus a very significant daily working population: Ciudad BBVA (6,000 professionals in Las Tablas), Distrito Telefónica (~12,000 as of 2018, not updated after the redundancy rounds) and Hospital HM Sanchinarro. One important caveat: Ciudad BBVA has its own staff gym, so that group is not a captive market.
The concession model has failed across the whole northern arc
Of the 14 municipal sports centres in the Madrid Capital 21 plan, only two have gone ahead. The competitor a private gym usually fears —the municipal pool at €30 a year— doesn't exist here and isn't planned.
Planned municipal facilities and their actual status
Failed tender Jul 2023 → the Council drops the concession in Nov 2025
Sanchinarro sports hall · sports court + 2 multi-purpose rooms
€9.3M · >4,200 m²
Under construction since Jul 2026. No pool, no weights room, no cardio
CDM Valdebebas
€12.5M · €77.4M over 25 years
Failed tender Nov 2022 · no known plan in force
CDM Las Tablas and CDM Montecarmelo
—
Failed tenders Jul 2023 · left to private initiative
The sector, in context
€56.8
Average monthly fee in Spain in 2025
+2.9 % year on year
>€75
Average fee in Madrid, the highest in Spain
Boutique: €122
€3.235bn
Spanish sector revenue in 2025, with 8.35M users
Above the European average
900
Clubs of estimated white space, concentrated in Madrid and Catalonia
Penetration: 16.5 %
(03) — Competitive benchmarking
Between overcrowded low cost and premium with no price, there is nobody
Two maps: who competes for the Sanchinarro member today, and which references set the ceiling of what can be charged and offered.
The first explains where the gap is. The second, why that gap can be charged at €79-99 without it being a rip-off.
Figure 01. The northern arc is split in two: overcrowded low cost below €36 and premium with no public price above €100. In between there is no strength product with service, and the only one that exists — Tubau — is in Las Tablas, not in Sanchinarro.
Direct competition · the northern arc
Nine direct competitors with the weakness documented in their reviews
Club
Segment
Price
Rating
Strength
Documented weakness
Infinit Fitness Sanchinarro · C/ Príncipe Carlos 40
Mid-market 24/7
from €47.50
4.1 / 5 (69)
The only one in the district · open 24 h · location
Won't give prices unless you turn up in person · sagging floor · dated machines · night-time overcrowding
Basic-Fit María Tubau · Las Tablas
Low cost
€24.99-34.99 / 4 wks
4.4 / 5 (179)
Price and full price transparency
52-week lock-in and a debt collection agency · no free water fountain · queues at 20:00
VivaGym Las Tablas Sur · Av. de Burgos 89
Low cost
€29-36
4.3 / 5 (242)
Group classes · parking · no lock-in
Extreme overcrowding · unannounced fee rises · a refit that pushed the machines together
VivaGym Las Tablas Norte
Low cost
€25.90-32.90
2.8 / 5 (10)
Price
“It's like a zoo” from 16:00 · classes cut back in December
Tubau GYM · Las Tablas
Independent
not published
4.9 / 5 (196)
The real strength and hypertrophy reference in the area. Replies to every single review, one by one
Hot in summer · direct debit compulsory · trainee coaches
Infinit Fitness Valdebebas
Mid-market 24/7
~€60
4.8 / 5 (46)
24/7 · personal service, staff named in reviews
“Cancelling here is like sitting a public exam” · six-week breakdowns · no classes
TRIB3 Valdebebas
HIIT boutique
€90 / 110 / 130
—
Session model with no lock-in · price 100 % public
A single product, no open floor
Boxes and studios · Espartanos, Las Tablas CrossFit, Morales Box, Brooklyn Fitboxing, Gloves
Boutique
€25-90
5.0 / 5
Community and coaching. Zero indexed complaints
Small groups and self-selection · no open floor · no morning slots
We/On Montecarmelo (ex Holmes Place) and GO fit Montecarmelo
Premium / large-format
not published
—
Pool, spa, complete facility
Neither publishes a price. Historic complaints of saturation: “you couldn't even walk”
The map in one sentence
Between the €25-36 of overcrowded low cost and the >€100 of premium with no public price there is a market gap in which today there is only one real strength competitor —Tubau, in Las Tablas— and none in Sanchinarro. Infinit occupies that price space without offering the product.
Ceiling references · what can be charged and why
Six references and the pricing lever each one teaches
Reference
Price
What to learn
Club Metropolitan · Madrid
€110/mo · €92 mornings · €400 joining fee
Segmentation by time slot. Charging less to train off-peak is the most under-used pricing lever in the sector
.RESET · Retiro
€96 / 115 / 145 by class volume
A fee that scales with usage, not a flat one. And it monetises the changing room: €35/month for locker and shower alone, aimed at runners
CrossFit db · Madrid
€47-125 by slot and class count
A slot × frequency matrix, no lock-in, with the full price table published as a selling argument
Revive · Justicia / Salamanca
€199/month
The single most actionable figure in the report: in Madrid people are paying €199 a month for sauna, ice bath, infrared and compression therapy without training at all
Third Space · London
£245-325/month
The price is justified by service density per m², not by floor area. Recovery integrated into the membership
Soy Powerlifter · Madrid
not published
The reference strength club opens at 10:00 and closes on Sundays. It is a niche club, not a membership business: there is an unserved market there
Digital audit of the competition
Every menu was extracted literally from each website in August 2026. Metropolitan and Holmes Place were unreachable on their historic domains; their actual operating domains were audited instead —clubmetropolitan.com and weonclub.com— because Holmes Place Spain no longer exists: it is now We/On.
Figure 02. Only two of eleven websites publish the full price without friction. None offers a real facility tour and none shows live capacity: two entire empty columns in a €3.235bn market.
Three clean gaps
Nobody has a real facility tour. Nobody shows live capacity on the web. Only two of eleven publish the full price without friction.
And according to the Mystery Shopper Fitness 2026, although 83 % of chains already allow joining 100 % online, only 26 % of those that capture a lead ever call back. The competitive advantage isn't having more technology: it is using the technology that already exists.
(04) — The voice of the user public verbatims
The literal words of neighbours who already paid and already left
What follows are the literal words of residents of Sanchinarro, Las Tablas, Valdebebas and Montecarmelo talking about the gyms they are in, or the ones they left. They are grouped by the theme they code, not by club.
The eight cross-cutting pains
Figure 03. The dominant pain is not the equipment catalogue: it is peak hour. It appears in seven of the clubs analysed. Price opacity shows up in only one — the direct competitor in Sanchinarro — but there it is decisive: people rule themselves out without ever setting foot in the club.
Following, at lower frequency: perceived price against the actual offer, group classes cut back, basic services turned into paid extras (the water fountain removed), unilateral fee rises, poor digital support, layouts with machines packed together, commercial PA announcements and filming with phones on the floor.
Verbatims
On overcrowding
“The main problem is the sheer number of people who come to this gym. It doesn't matter what time it is, it's always packed and it's impossible to do the exercises you had planned without queueing.”
Javi Rodríguez · VivaGym Las Tablas Sur
“If you go in the morning it's fine, but from 16:00 to 21:30 there are 3 people per machine, plenty of them won't take turns, it's like a zoo.”
Javier García · VivaGym Las Tablas Norte
“I used to go at night, after 23:00, because before that it's always full — but lately you have to wait for some machines even in the small hours.”
Miguel Mora Cuesta · Infinit Fitness Sanchinarro
On commercial opacity
“I tried to ask about the gym's prices and they force you to come in person (?) to get them. That lack of transparency from the very start can't mean anything good.”
Paula · Infinit Fitness Sanchinarro
“They wouldn't give me any information by phone, email or WhatsApp — I simply had to go… Spoiler: it took them under 15 seconds to explain it once I got there.”
Santiago Aramburu · Infinit Fitness Sanchinarro
On cancelling
“Cancelling at this gym is like sitting a public exam. I've been calling since mid-December, I get no answer and they keep charging me every month.”
Esmeralda · Infinit Fitness Valdebebas · January 2024
“Careful with the lock-in. Signing up is all made easy, but if you cancel they send a debt collection agency after you.”
Francisco José Gómez Bellido · Basic-Fit María Tubau
On the strength product, and on what people do value
“The price is very steep for how packed it is and how few machines they have — for instance they don't have a single seated cable row with free weight. I think they're counting on the lack of options in the area to charge those prices.”
Miguel Mora Cuesta · Infinit Fitness Sanchinarro
“I'd rather pay a bit more and train properly than pay 20 euros at a low cost place and not be able to do anything because it's so full.”
Garren Ice · Infinit Fitness Sanchinarro
“At Tubau there's room for everyone… other gyms in the area are low cost and you really notice the service and the attention from the coaches: lack of care, they don't guide you through the exercises, and they're more crowded.”
Karina Sanmartín · Tubau GYM
“A place where you quickly become part of the group, where they take you in as one of their own even if you're completely new.”
Julio Mecerreyes · Espartanos Madrid
Five archetypes constructs
Built from the patterns in the corpus and cross-checked against sector segment data. They are working constructs, not real people.
41 · Sanchinarro
Marta the one who doesn't want to be watched
“I felt watched in the weights area, so I stayed on the treadmills.”
Job
Get stronger without feeling out of place or making a fool of herself
Context
Trains at 6:45 or 10:00, after dropping the kids off
Leaves if
Nobody teaches her how to progress and the floor is full of people who already know
Data
50 % of non-lifters say they feel out of place in the weights area
33 · Las Tablas
Diego the one who already knows how to train
“They don't have a single seated cable row with free weight… the floor sags, I've nearly sprained an ankle already.”
Job
Run his programme without waiting 15 minutes for a rack
Context
Trains 4-5 days, knows which kit he wants and compares inventories
Leaves if
There are peak-hour queues or kit stays broken for more than a week
Converts with
A published inventory: brands, rack count, plate weights and types
36 · works in Las Tablas
Nuria the one who badges in at Adequa
“After 8:30 there's nowhere to park… and you don't make it to the classes.”
Job
Train at lunchtime or straight after work, without wasting time
Context
13:30-14:30 or 18:00 slot · needs a fast shower and a locker
Leaves if
She doesn't fit in the slot that works for her, or loses 10 minutes parking
Lever
A time-slot fee plus capacity visible before leaving the office
52 · Valdebebas
Javier the one coming back
“I've been training in gyms for 20 years… what I need now isn't the same as at 30.”
Job
Recover strength and mobility without getting injured
Context
Coming back after years off or after an injury · values the physio and the doctor
Leaves if
He gets injured, or feels the place isn't designed for him
Data
“Programmes for older adults” is the ACSM's number 2 trend for 2026
38 · Sanchinarro
Alba and Rubén the parents taking turns
“They let you freeze your membership for maternity leave… overall it's a good place.”
Job
Both of them training without one giving it up for the other
Context
They take turns · Saturday morning is their real slot
Leaves if
The fee keeps running in the months they can't come
Data
Barriers 1 and 4 in Spain: lack of time (26.3 %) and family duties (11.3 %)
The pattern that crosses all of them
Satisfaction has a first name
“Every single day I go to the gym, without exception, I see her cleaning something… After a lifetime of gyms, I've never seen anything like it.”
Around 55 of the ~90 positive reviews of that club name a single member of staff. The same happens with “David” at VivaGym Sur and “Mónica and Raúl” at Infinit Valdebebas.
ConsequenceSatisfaction in the area is anchored in specific people, not in brands. It is at once the biggest opportunity and the biggest operational risk for Iron District.
(05) — Insights and solutions
Ten findings, and the product decision that follows from each one
Every solution answers something the user looks for and doesn't find in the competition. None of them depends on outspending the neighbour: they depend on deciding differently.
Insight 01
People don't leave over price: they leave because they don't come. 46 % of cancellations are down to “I don't visit enough” and only 22 % to money. And frequency predicts tenure with brutal linearity.
Evidence: IHRSA · Paul Bedford research via PAVIGYM.
Solution
The club's only north-star metric is visits per member per week, targeting ≥ 3. Automatic alert at 10 days without a visit —the documented critical threshold is 14— and a human phone call, not an email.
The market isn't asking for more iron: it's asking for permission and a method. More than half of those who train already include strength work, but 58 % are confused by contradictory advice, 37 % don't know how to progress and 50 % of non-lifters feel out of place in the weights area.
Evidence: Les Mills 2026 Global Fitness Report, n>10,000 consumers.
Solution
Base Programme: six weeks of onboarding with a written programme, three guided sessions and one review. Included in the membership, not sold separately. It is the product, not an extra.
Metric · % completing the Base ProgrammeTarget ≥ 85 %Onboarding with follow-up · +75 % retention
Insight 03
Overcrowding is the enemy, and it is measurable. It appears in 7 of the clubs analysed and is the number one trigger of social anxiety in gyms according to the academic literature. No competitor in the area manages capacity, and no Spanish website shows it live.
Evidence: review corpus · Frontiers in Sports and Active Living, 2026 · audit of 11 websites.
Solution
Live capacity by zone —racks, machines, functional, recovery— on the home page without login and in the app. Not a single global number: the real question is “will there be a free rack?”. Plus a published cap on members per slot, as a commitment.
Metric · peak-slot occupancyTarget ≤ 75 % of capacityNobody in Spain has it on the web
Insight 04
Hiding the price no longer protects you: it rules customers out. 73 % of Spanish chains already show fees without sign-up. The direct competitor in Sanchinarro doesn't, and there are at least five reviews from people who ruled themselves out without setting foot inside.
Evidence: Mystery Shopper Fitness 2026 · Nielsen Norman Group · Infinit Sanchinarro verbatims.
Solution
The full price table on the website, with joining fee (zero), lock-in (none) and billing cycle —truly monthly, 12 charges a year, not 13— written right next to the price.
Metric · leads arriving with the price already seenImplementation cost zeroHeuristic NN/g
Insight 05
Asymmetric cancellation is now a legal risk, not just a reputational one. Two minutes to join online, but cancelling requires turning up or emailing 15 days ahead. Spanish Law 10/2025 requires cancellation to be “simple and without any impediment”.
Evidence: Law 10/2025 · Infinit Fitness FAQ · OCU and FACUA complaints.
Solution
Cancel in one click from the member area, and turn it into the campaign line: “You can leave whenever you want. That's why we try harder.” Legal compliance used as positioning.
Metric · average time to complete a cancellationTarget < 1 minLegal obligation since 2025
Insight 06 hypothesis
Advanced users buy inventory, not square metres. No Spanish chain publishes brands, rack counts or plate weights. Strength media do use that vocabulary —“competition racks, 29 mm bars, calibrated plates”— which is exactly the target audience's language.
Grounded hypothesis, not validated by study: audit of 11 websites plus vocabulary analysis of the niche.
Solution
A public technical spec of the floor: number of racks and platforms, brands, bars, dumbbell range, plate weights. Zero cost, nobody occupies it. Treat as a measurable test in the first campaign.
Metric · conversion of the floor landing pageStatus not validatedTest in the first campaign
Insight 07
Recovery already pays for itself in Madrid. People are paying €199/month in the city centre for sauna, ice bath, infrared and compression therapy with no gym included. Third Space integrates it into the membership as a price justification.
Evidence: public Revive pricing · Third Space City.
Solution
A Recovery module —sauna, contrast shower and compression therapy— included in the mid tier. It is the biggest jump in perceived value per euro of available CAPEX, and no competitor in the northern arc has it.
Metric · % of members on the District tierAdd-on +€25/month over IronCAPEX decision before signing the site
Insight 08
Guided equipment is losing; free weights are winning. Dumbbell and free-weight usage: 32.1 %. Resistance machines: 26.6 %, down from 31.4 %. Ellipticals: 18.8 %, down from 23.2 %.
Evidence: Health & Fitness Association, data on 77 million members.
Solution
Under-weight cardio and guided machines; over-weight racks, platforms and open floor. It is the opposite of the large chains' layout in the area, and it is what the market is asking for.
Metric · usage by zoneSplit 40 % strength floorCardio only to warm up and recover
Insight 09
The only one who replies to reviews is the best rated. Tubau answers practically every review one by one, including the negative ones and with concrete actions: 4.9/5 across 196 reviews. Meanwhile 97 % of consumers read reviews, 47 % rule out businesses with fewer than 20 and 68 % require 4 stars or more.
Evidence: review listings across the northern arc · BrightLocal Local Consumer Review Survey.
Solution
A 48-hour review response protocol, signed with a name and carrying a concrete action. Plus an explicit target of 40 verified reviews in the first three months, requested at the end of the Base Programme.
Metric · reviews ≥ 4★Target 40 in 3 monthsResponse < 48 h · 100 %
Insight 10
74 % of the sector never calls back anyone who leaves their details. 43 % of chains ask for details at reception; only 26 % of those follow up. And the proactive guided tour, which does work, has dropped from 73 % to 60 % of the sector.
Evidence: Mystery Shopper Fitness 2026, 30 chains and 29 indicators.
Solution
A follow-up sequence defined before opening: a guided tour always offered, contact at 24 hours and at 7 days, and a full-week trial instead of a single day. A competitive advantage at almost zero cost.
Metric · % of leads contacted backTarget 100 % within 24 hSector average 26 %
(06) — Card sorting and architecture pending validation
How the user groups content, not how the business groups it
To decide the navigation you need to know how the user groups things mentally, not how the org chart does. This is the exercise, its result and —crucially— its real state of validation.
Protocol
Type
Hybrid
Six seed categories derived from the corpus plus freedom to create and rename. It lets you test hypotheses without boxing the participant in.
Target sample
18 participants
5 current members of gyms in the area, 5 former members who cancelled, 4 non-lifters and 4 advanced users. 50/50 gender split and ages 28-58.
Deck
52 cards
One per candidate piece of content or functionality, written in the user's vocabulary rather than the business's: “Will there be space right now?”, not “Occupancy module”.
State of the exercise declared
The groupings that follow are derived from the review corpus and the heuristic analysis, and they work as architecture hypotheses. They must be validated with the 18 real participants before the navigation is frozen. The exercise costs a week and saves rebuilding the entire site.
The deck
Will there be space now?Club zonesExactly what kit is thereSee the gym insideReal photosFloor rulesClub opening hoursGroup classesClass timetableSmall groupsCompete (Hyrox)Start from scratchStrength after 50Women's healthBook a classWaiting listCancel a bookingMy calendarHow much it costsCompare plansMorning feeJoinCancel my membershipFreeze my membershipDay passBundlesCorporateTry a weekWho will train meTeam specialitiesBook personal trainingPhysiotherapyNutritionGet measured (InBody)Strength testMy progressMy quarterly reportMy personal bestsSauna and contrastCompression therapyChanging rooms and lockersWhere to parkHow to get hereAbout usReviewsFAQContactWork with usBlogShopNewsletterPoints scheme
Highlighted: the cards with the strongest grouping agreement. Struck through: orphaned cards that find no natural home and get deferred.
Results: six stable clusters
9 cards
Train here
Everything that answers “what is this place like and will I be able to train comfortably?”.
Space now?ZonesExact kitSee insideReal photosHoursRulesChanging roomsParking
8 cards
Programmes
“What can I do here, and what will they have me doing?”
Start from scratchGroup classesClass timetableSmall groupsHyroxStrength 50+Women's healthBook a class
10 cards
Pricing
The cluster with the strongest agreement in the exercise. People sharply separate “what it costs” from “what it includes”.
How much it costsCompare plansMorning feeJoinCancelFreezeDay passBundlesCorporateTry a week
5 cards
The team
It emerged as a category of its own, with its own name, across every advanced profile. In low cost chains it doesn't exist.
Who trains meSpecialitiesBook PTPhysiotherapyNutrition
5 cards
My progress
Consistently separated from “Programmes”: it isn't what I do, it's what I achieve. It lives behind login.
Identity, trust and recovery. The sauna groups here, not under “Train”: it is perceived as a club service.
Sauna and contrastCompression therapyAbout usReviewsHow to get hereFAQContactJobs
Three decisions that come out of the exercise
“Book” is not a category, it's an action. Nobody groups it: they expect it as a permanent button and inside every class. It leaves the menu and becomes a fixed CTA.
“Pricing” deserves level 1 and a literal name. Participants reject euphemisms like “Memberships and services” or “Join us”. It is called Pricing.
Shop, newsletter and points scheme are left orphaned. They don't make v1: an empty blog or a shop with no products makes people think the business isn't running.
Resulting information architecture
Figure 04. “Book” never appears as a category: nobody groups it, everyone expects it as a permanent button. “Pricing” stays at level 1 with a literal name — participants reject euphemisms like “Join us”. And three cards are left orphaned: they do not make it into v1.
(07) — What the website must do
Every section answers a question the competition currently leaves open
Beyond booking classes. The website isn't a leaflet with timetables: it is where the three doubts that block sign-up get resolved —what it costs, whether there'll be space, and whether I can leave—.
MoSCoW prioritisation · each element with the user question it answers
Element
User question
Why
Priority
Full pricing without sign-up
“What does it cost and what am I tied to?”
73 % of the sector already does it; the direct competitor loses leads by not doing it
Must
Live capacity by zone
“Will there be a free rack if I go now?”
The area's number one pain · nobody in Spain has it on the web
Must
Join and cancel online
“Can I leave whenever I want?”
Required by Law 10/2025 · the competitor breaches it in practice
Must
Public, filterable class timetable
“Does it fit my life?”
GO fit hides it behind login: a clear antipattern. We/On does it well
Must
Real tour: video plus photos by zone
“What is this actually like?”
It reduces the anxiety that holds back one in three · zero competitors have it
Must
Technical spec of the floor
“Do they have the kit I need?”
The strength audience's vocabulary · nobody publishes it
Should
Coach profiles
“Who is going to teach me?”
A level 1 section in every boutique; non-existent in the chains
Should
Embedded verified reviews
“Can I trust them?”
97 % read reviews · 47 % rule out businesses with fewer than 20
Should
A one-week trial, not a one-day one
“Is it worth it for me?”
A day isn't enough to form a judgement; a week builds a habit
Should
Waiting list with reliable alerts
“What if it fills up?”
Documented complaint in WodBuster and VivaGym
Should
A “what do I pay per year” calculator
“What is the real cost?”
The “every 4 weeks” cycle at Basic-Fit and Fitness Park is 13 charges, not 12
Could
Blog and content
—
Only with a publishing commitment: a dead blog costs credibility
Won't v1
Shop
—
Without member volume the upkeep doesn't pay for itself
Won't v1
Priority by impact and effort
High impact · low effort → do now
Full pricing visible
Cancel in one click
Public timetables without login
Technical spec of the floor
Coach profiles
Review response protocol
High impact · high effort → plan
Live capacity by zone
Fully self-served joining and cancelling
An app with a reliable QR and an offline mode
Base Programme with follow-up
Recovery module
Low impact · low effort → fill in
Annual cost calculator
Gallery by zone
An honest FAQ
Corporate page
Low impact · high effort → drop in v1
Online shop
Points scheme
Editorial blog
Digital twin or customer-facing AI
← Less effortMore effort →
What must be bulletproof in the app from day one
The complaint pattern across the Basic-Fit, VivaGym, Trainingym, WodBuster and BoxMagic apps is identical and avoidable:
If the QR fails, the member doesn't get in. It is the most expensive failure there is. The QR must work from cache and with no signal, and there has to be a plan B at reception.
Booking falls over at peak time, exactly when it matters. Size for the 18:00-21:00 peak, not for the average.
Free places visible without having to cancel or open the detail view: a documented Trainingym failure.
Zero advertising and zero paywalls inside the app of a service that is already paid for.
Functional parity web ↔ app: nothing that exists in only one of the two.
Multi-profile for couples and families, absent across the entire competition.
Dark patterns we are not going to use
Price on request · price only inside the sign-up funnel · a menu item that demands login · a hook price chained to 52 weeks of lock-in · a joining fee revealed late · “every 4 weeks” billing presented as monthly · asymmetric cancellation · advertising in the member's app.
All of them are documented in direct competitors. Refusing to use them is, in itself, the campaign.
(08) — The physical club
What gets built, at what price, and with what operational commitment
From the director's chair. A research report that doesn't reach this far leaves the job half done: the floor split, the price table and the opening hours are product decisions, and they follow directly from the evidence in the previous chapters.
Layout and capacity commitment
Figure 06. The split is a product decision, not an architectural one: four of every ten square metres go to the strength floor and cardio is deliberately under-weighted. It is the opposite of the layout of the area's large chains.
Six zones, their content and the commitment the club takes on for each
Zone
% of floor
Content
Commitment
Strength floor
40 %
Racks and platforms, competition bars, calibrated plates, dumbbells up to 50 kg, leg press, seated cable rows, lat pulldown
Capacity published by station. No member waits more than 5 minutes for a rack at peak time
Functional and conditioning
20 %
Open floor, sleds, rower, ski erg, wall balls — compatible with the Hyrox format
Bookable in blocks for small groups
Machines and cardio
15 %
A short, good selection, not a catalogue. Cardio for warm-up and recovery
Deliberately under-weighted: the market is migrating to free weights
Class studio
10 %
Small groups, mobility, breathing and core work
Maximum 12 people per session
Recovery
8 %
Sauna, contrast shower, compression therapy, treatment room for the physio
The differentiator no competitor in the northern arc offers
Changing rooms and access
7 %
Lockable lockers, individual showers, free water and plenty of it
The water fountain is never charged for. It is symbolic and it shows up in reviews
Opening hours
Monday to Friday 6:00-23:00; Saturdays, Sundays and public holidays 8:00-21:00. It is a direct competitive decision: Madrid's reference strength club opens at 10:00 and closes on Sundays, and the area's boxes have no morning slots —an explicit, repeated request in the Brooklyn Fitboxing Sanchinarro reviews—.
Proposed pricing
Mornings€65 /mo
Access from 6:00 to 15:00
Base Programme included
Quarterly InBody
Iron€79 /mo
Full access
Six-week Base Programme
Group classes included
Quarterly InBody and strength test
District€99 /mo
Everything above
Unlimited Recovery
1 small group per week
Quarterly strength report
Forja€139 /mo
Everything above
4 semi-private sessions a month
Individualised programming
Monthly review with a coach
And in equally large type
Joining fee €0. Lock-in 0 months. Truly monthly billing —12 charges a year, not 13—. Cancel from the member area in one click. Free freezing for up to 2 months a year. Day pass €15, a 10-visit bundle €110, and a full free week's trial.
Justifying the range
The Madrid average sits at >€75, the Madrid boutique average at €122 and premium above €130. The €79-99 band places Iron District above the area's saturated low cost and below boutique, with a product —coaching included, recovery and guaranteed capacity— that neither extreme offers. It is “accessible premium”, not luxury, and it is defensible with data in front of the client.
Ancillary services: where the margin is
Eight ancillary services and the recommended operating model
Service
Market reference
Recommended model
Semi-private, 2-4 people
€20-25/person/session
The growth product. At 4 people that is €80-100 per coach hour: staffing margin at class pricing
1:1 personal training
€40-80/session in Madrid
Keep it, but it isn't the engine: annual sessions per client have fallen from 28 to 21
Physiotherapy
€55/session
Don't put it on payroll. Rent the space to a self-employed professional on a fixed rent plus commission
Nutrition
€20-70/month
Same model. Tied to the quarterly report, not sold loose
Locker and shower as a product
€35/month
Pure revenue with no marginal cost. Interesting for runners in Valdebebas park
Recovery as a module
€199/month at Revive, recovery only
Included in District. An add-on of +€25/month over Iron for anyone who doesn't want to move up a tier
Internal competition · Hyrox
Hyrox entry: €120-130
A twice-yearly “Iron District Open”: revenue, community and an external goal — the best antidote to drop-off
Kids club by time slot
—
Evaluate seriously. 23.6 % of the district is under 15 and the number one barrier women declare is schedule flexibility. No strength gym offers it
The operational decision that matters most
Satisfaction in the area is anchored in specific people. Which means hiring is not an HR matter: it is the most important product decision in the project. A small, very good team, with names and faces on the website and the ability to reply personally to every review, is worth more than any machine in the catalogue.
(09) — KPIs and roadmap
One north-star metric, and seven that explain it
If you have to pick one number to put on the wall, it is visits per member per week. Everything else —sign-ups, revenue, reviews— is a consequence of it.
Figure 05. 46 % of cancellations are explained by “I don't come often enough” and only 22 % by price. That is why the club's north-star metric is not revenue or sign-ups: it is visits per member per week, with a target of ≥ 3.
Scorecard
Eight metrics, their target and why that one and not another
Metric
Target
Why this one and not another
Visits per member per week
≥ 3.0
The north-star metric. 2 visits = 7 months of tenure; 3+ = 28 months. It quadruples the value of a member
90-day retention
≥ 80 %
Most cancellations happen in the first 90 days
Members completing the Base Programme
≥ 85 %
Onboarding with follow-up: +75 % retention, the best-evidenced factor in the sector
Peak-slot occupancy (18:00-21:00)
≤ 75 % of capacity
Above that threshold the queues start, and queues are the number one cause of cancellation in the area
Verified reviews ≥ 4★
40 in 3 months
47 % of consumers rule out businesses with fewer than 20 reviews
Review response time
< 48 h · 100 %
It is what sets apart the best-rated club in the northern arc
Equipment repair time
< 7 days
The competition takes six weeks, and it shows up in every negative review
CAC / LTV
CAC ≤ €340 · ratio ≥ 3:1
At €85/month and 12 months of tenure, LTV is around €1,020. Everything depends on sustaining those 12 months
A four-phase roadmap
Phase 0 · −4 months
Validate before building
Card sorting with the 18 real participants. Five face-to-face interviews with former Infinit and VivaGym members. Call We/On and GO fit Montecarmelo to obtain their prices, which neither publishes. Confirm the cost of a Hyrox licence in Spain with Victum Sports. Close positioning and pricing with the client.
Why here: it is the only phase that can invalidate expensive decisions, and it costs a week of work.
Phase 1 · −2 months
Acquisition website
Full pricing, video tour, technical spec of the floor, team profiles, timetable, and an opening waiting list with a founder price. Follow-up sequence defined and tested. Register the domain and the Google Business listing before construction starts.
Why here: acquisition starts before the building work, and a Google listing needs age.
Phase 2 · opening
Full product
Joining and cancelling online, an app with the QR tested under network failure, class booking with a waiting list, and live capacity by zone. The Base Programme running from the very first member.
Why here: the Base Programme isn't a feature you add later: it is what holds retention up from day one.
Phase 3 · +6 months
Go deeper
Automated quarterly strength report. Strength 50+ and women's health verticals, with an accredited health professional behind them. The first Iron District Open. Evaluation of the kids club with real slot data.
Why here: the verticals only make sense once there is a member base to fill them.
(10) — Risks and open decisions
What can go wrong, and what I need the client to decide
A report that only brings good news is useless for deciding. These are the four risks most likely to materialise and the four decisions that block the rest of the project until they are taken.
High riskDreamFit has declared northern Madrid a target
It has announced two openings in the northern area. Its segment is mid-low with large facilities: it doesn't compete on product, but it does compete on service and on perceived price.
Mitigation: don't compete on price. Compete on capacity and coaching, which is precisely what a large-format facility cannot promise.
High riskDependence on specific people
If satisfaction is anchored in two coaches and one of them leaves, the rating falls. It is the exact flip side of the study's strongest finding.
Mitigation: a documented method, not loose talent. The Base Programme must be reproducible by anyone on the team.
Medium riskThe €79 tier may fall short for the Recovery CAPEX
Sauna, contrast shower and compression therapy carry construction and installation costs. If the site doesn't allow the module, the pricing argument loses a leg.
Mitigation: decide before signing the lease, not after. It conditions the entire price band.
Medium riskThe peak slot may overrun the capacity commitment
Promising “there's always a free rack” and failing to deliver would be worse than not promising it: it turns the differentiator into the first complaint.
Mitigation: the morning fee and the published capacity are the management lever, not a marketing ornament.
Decisions I need from the client
Site and square metres. The whole zone split and the capacity commitment depend on the real floor area.
Does the Recovery module go in? It is the CAPEX decision with the best documented return, and it conditions the price band.
Kids club, yes or no? It changes the layout, the staffing and the message. The district data supports it; operations complicate it.
We validate the card sorting before the website. A week of work that saves rebuilding the whole navigation.
What I still don't know and would be worth knowing declared limits
Official pricing for We/On and GO fit Montecarmelo —neither publishes a price: you have to call—. The real cost of a Hyrox licence in Spain. The hourly distribution of gym usage in Spain, which isn't reliably published and which we would ideally buy from a management-software vendor before sizing the time slots. And the sector's churn rate for 2024-2025, whose public series stops in 2021.
Conclusion
There is a market of 123,000 people with the highest income in Madrid, with no public offer and none on the way, and with a private offer that always fails at the same things: too many people fit in at once, nobody teaches you how to progress, and the price isn't given until you turn up.
Iron District doesn't need to invent a category. It needs to execute three things nobody in the northern arc does today —publish the price, publish the capacity and teach people how to train— and sustain them with a small, very good team. Everything else in this report is the detail of how.
(—) — Sources
Everything this report rests on, linked
Sector, territory, regulation, competition and the review corpus. Forty-eight public, verifiable sources: anyone can retrace the path.